Why the oversupply narrative missed the turn, where the region’s demand is actually coming from, and how to read a market the headline vacancy rate can’t explain.
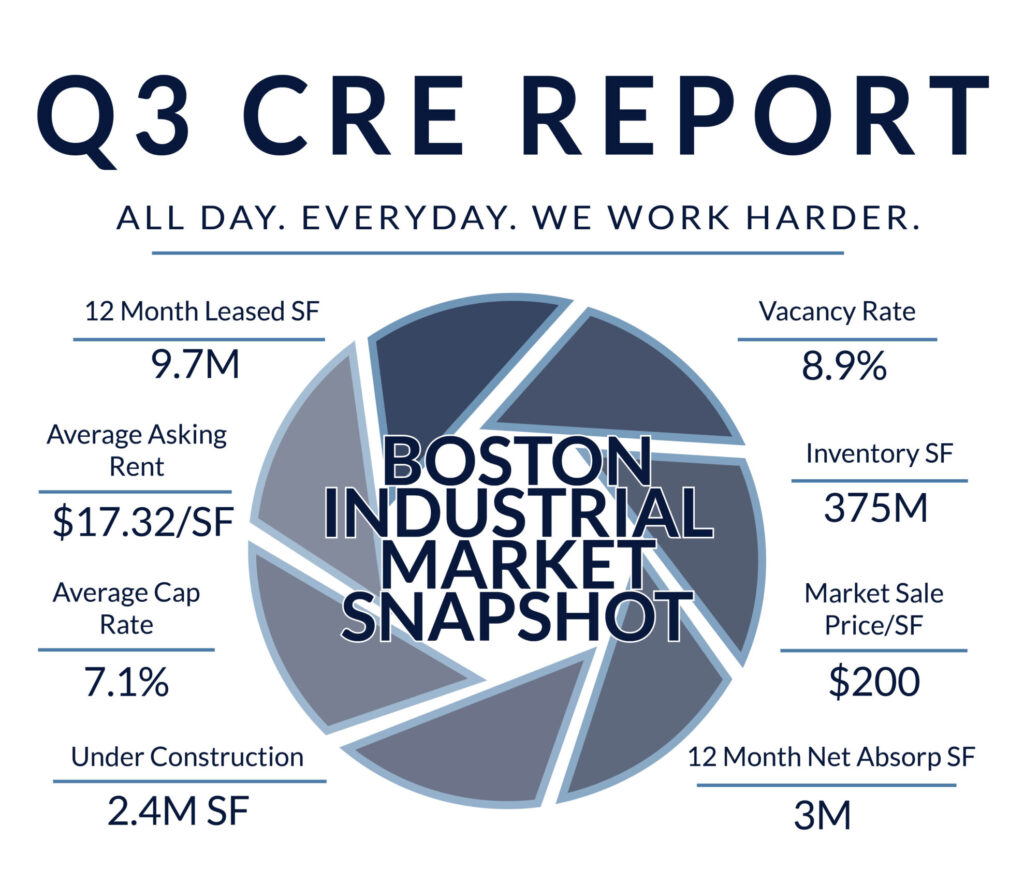
For two years the industrial story was oversupply: a record wave of pandemic-era construction landing just as demand cooled, and a steady drumbeat of warnings that developers had gotten ahead of themselves. That wave has crested, and the numbers have quietly turned. Nationally, industrial vacancy compressed to 6.8% at midyear – the first meaningful decline since mid-2023 – as tenant demand outpaced new deliveries and leasing hit its fastest pace since mid-2022.
Nowhere is that clearer than north of Boston. The North submarket – a broad, sought-after belt running from the Route 128 and I-93 corridor (Wilmington, Woburn) up through the Merrimack Valley (Andover, Lawrence) and out to the North Shore (Peabody, Danvers), within highway reach of more than half of Greater Boston’s population – led the metro in move-ins this quarter, posting three of its five largest. The broader Route 128 ring that had absorbed the brunt of the oversupply is now stabilizing as that space gets re-tenanted. Greater Boston as a whole is tightening right along with it: the region posted its strongest first half since 2022, pulling vacancy down to 7.6% even as new speculative construction slowed sharply. And the demand driving it isn’t the e-commerce names that defined the last cycle; it’s manufacturing, third-party logistics, life-science production, and food distribution – users that need the right building in the right place, not just any four walls.
The numbers behind the turn are decisive. National net absorption nearly doubled quarter over quarter and jumped sharply from a year earlier, as space that had been quietly shadowing the market finally got leased. The newest, largest Class A warehouses – the million-square-foot boxes everyone worried were overbuilt – tightened to under 6% vacancy, and big-box leasing surged year over year as occupiers returned to strategic, expansion-driven commitments rather than short-term stopgaps.
The forward indicator matters even more than the current one: the construction pipeline is still running far below its 2022 peak. Vacant new supply is being absorbed faster than it’s being replaced, and that is precisely how a tenant-favorable market becomes a landlord-favorable one. The concessions that defined the trough – free rent, oversized improvement allowances, flexible terms – are already beginning to erode. The occupiers who locked in deals at the bottom now hold an advantaged position over everyone facing a renewal in the next 12 to 18 months.
Put numbers to it and the turn is unmistakable. Greater Boston absorbed 2.3 million square feet in the second quarter alone – more than the entire prior year – and nearly 4 million across the first half. The sharpest improvement came in the newest Class A product, the very space that had carried most of the market’s vacancy: it posted a 320-basis-point drop in a single quarter as tenants moved on modern, high-clear-height buildings.
Demand has broadened well beyond a few marquee deals, though those are striking on their own – led by a 617,000-square-foot logistics lease in Hopedale, the largest in the metro since 2020, with major commitments also in Milford, Taunton, and Franklin. Beyond the strength up north, the picture varies by corridor: big-box users are competing for increasingly scarce large blocks out along I-495 and Route 146 to the west, while the South market remains the softest corner of the metro.
This is a different, and more durable, demand base than the last cycle’s. Nationally, third-party logistics providers and manufacturers now account for the majority of leasing, powered by reshoring, federal manufacturing incentives, and spillover from data-center construction. New England carries a regional accent on top of that: life-science manufacturing and biotech logistics, food distribution, and last-mile delivery serving one of the densest, most affluent populations in the country.
The distinction is more than academic. The e-commerce land-grab of 2020 and 2021 was a race for square footage; today’s users are pickier and stickier. A contract manufacturer or a cold-storage food distributor needs specific power, specific clear height, specific loading – which makes the right building far harder to replace and the right location far more valuable.
Flex sits where two trends meet. The region’s life-science sector is still normalizing after its own building boom, with lab availability elevated and some owners repositioning R&D and lab space back toward industrial and flex uses. That cuts both ways: it adds competing supply, but it also creates value-add opportunity in well-located flex that can serve light manufacturing, lab-adjacent, or logistics users. The Route 128 corridor, where older mid-box and flex inventory is concentrated, is where that overhang shows up most – and, as the ring stabilizes, where the repositioning and value-add plays will cluster over the next few years.
Industrial is not a monolith, and the metro average hides more than it reveals. A single 7.6% figure spans modern, high-clear-height Class A space leasing quickly and older, pre-2020 boxes being handed back and left to sit. Building vintage, clear height, power capacity, and loading configuration decide whether a space competes at all. A “tight” submarket can have a modern building sitting empty for want of power; a “loose” one can be exactly the right home for the right user at the right basis. And asking rents near record highs mean little until you net out concessions – effective rent is the number that actually clears a deal. The story is always in the details the headline leaves out.
We underwrite the building and the submarket, not the metro average. That means real absorption versus availability in the specific submarket rather than the regional number; the physical asset matched against the user’s operation – clear height, power, dock doors, trailer parking, zoning; effective rents net of concessions, not just the asking rate; and, for owners weighing a lease, tenant credit and use fit. For occupiers, we map where leverage still exists before it disappears. For owners and investors, we separate a genuine location problem from a fixable building problem – often the difference between a pass and a value-add buy. It’s the same discipline we bring to retail, applied to a different set of numbers: know before you commit.
Industrial’s oversupply era is ending, New England is tightening in the corridors that matter, and the demand base underpinning it is more durable than the one that drove the last cycle. But a rebalancing market with a widening quality gap rewards precision, not reaction. Whether you’re renewing a lease before the concessions vanish, weighing a distribution facility, or repositioning an older flex building, the winners will be the ones who read the submarket and the asset – not the headline.
Whether it’s a distribution building, a manufacturing facility, or flex space anywhere across Massachusetts, southern New Hampshire, or Rhode Island – that’s the analysis we do every day. Let’s talk.
Written by Tom Blaisdell
Director of Sales Development
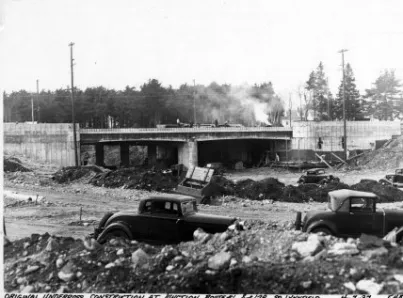
Route 128 was once known as “America’s Technology Highway.” Beginning in the 1950s, the corridor became one of the nation’s first major high-tech clusters, attracting companies such as Raytheon, Polaroid and Digital Equipment Corporation. This growth fueled the development of office parks, R&D facilities and industrial properties throughout Greater Boston. Today, Route 128 remains a key commercial real estate corridor, home to leading technology, life science and advanced manufacturing companies.
WE BELIEVE EVERY REAL ESTATE CHALLENGE HAS A SOLUTION.
WE BRING
ALL DAY. EVERY DAY. WE WORK HARDER.
The Stubblebine Company/ CORFAC International produces value for our clients by providing creative solutions and aggressive marketing in the greater Boston commercial real estate marketplace by putting the goals and objectives of our clients first and adhering to biblical principles.
We combine suburban Boston expertise in the industrial, flex and office property markets with direct senior management involvement with clients and properties to produce unparalleled results for clients locally, regionally, nationally and internationally through our affiliation with CORFAC International, a top five global network of entrepreneurial commercial real estate services firms.